MAM
GUEST COLUMN: How quick commerce is changing the way FMCG brands build visibility and drive growth
The digital shelf is changing discovery, packaging, promotions and brand loyalty

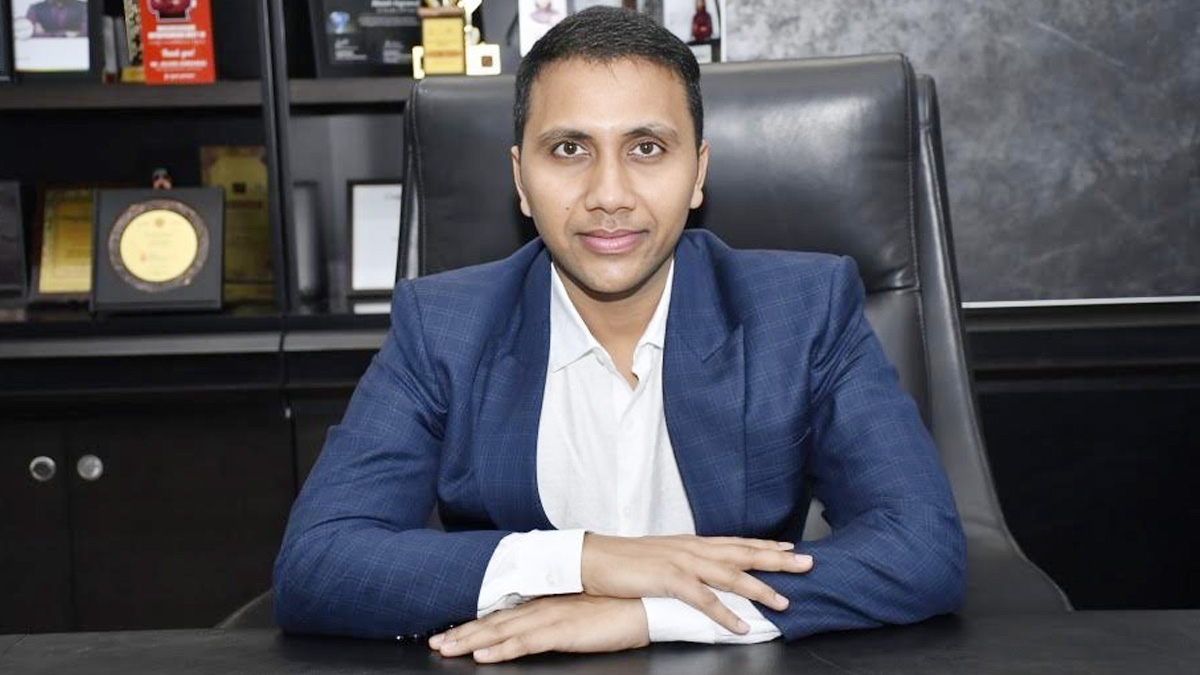
MUMBAI: As Indian consumers increasingly shift from planned grocery shopping to on-demand purchases, quick commerce is reshaping how FMCG brands build visibility, drive discovery and convert demand. The digital shelf is becoming as important as physical shelf space, with search rankings, product imagery, ratings, availability and offers influencing purchase decisions. In this guest column, Akash Agrawalla, co-founder, ZOFF Foods, examines how quick commerce is changing consumer behaviour, why packaging and assortment need to evolve for the digital shelf, how advertising and commerce are converging, and why brands must look beyond discounts and delivery speed to build lasting consumer relationships and unlock growth.
Ten-minute delivery may be the most visible promise of quick commerce, but its larger impact on FMCG is happening much further upstream. The consumer journey is evolving from the physical aisle to the digital screen, creating new opportunities for brands to be discovered, evaluated and chosen. A consumer who once walked through a supermarket, picked up a few packets and compared products is increasingly making similar decisions on a phone. Search visibility, product imagery, ratings, availability and relevant offers are becoming important parts of that decision-making journey.
Quick commerce is therefore emerging as much more than an additional distribution channel. It is creating a new digital shelf for FMCG brands — one that can expand consumer access, accelerate discovery and give brands new ways to understand and respond to changing consumption habits.
The Shelf has moved to the screen
For decades, FMCG companies focused on physical shelf space. Distribution mattered. The number of outlets mattered. Eye-level placement mattered. Retailer relationships mattered. Packaging had to stand out when viewed from a few feet away.
Now much of that competition is moving onto a phone screen. A consumer searches for jeera, garam masala, makhana or a ready-to-cook gravy and sees a limited number of products. The brands that appear first have a clear advantage. Product photography becomes more important. So does the title, the rating, the offer and whether the pack can communicate anything when it appears as a small thumbnail.
Being listed is now only one part of the opportunity; being visible can create a stronger advantage. The digital shelf also keeps evolving. What a consumer sees can depend on location, availability, search terms, recommendations and paid visibility. For brands, this raises a valuable question: If the consumer can see you clearly, how much more powerful can your availability become? That is something FMCG companies will have the opportunity to think about much more strategically.
The pack has to work harder
The supermarket gives consumers time to look around. They can pick up a packet, turn it around, compare it with another product and sometimes discover brands they had not planned to buy. On quick commerce, the decision can be much faster. A consumer searches for a product and is immediately presented with several choices. A familiar brand may sit next to a newer one. There may be a discount on one, better ratings on another, or a pack that simply looks clearer.
This creates a new opportunity for packaging. Does the pack still work when it is viewed on a small screen? Can the consumer tell one variant from another? Can she understand what makes the product different? If one product costs slightly more, is there an obvious reason why? These questions matter because the physical pack is now also part of the digital sales experience. For many FMCG products, the pack photograph is effectively the first advertisement the consumer sees at the point of purchase. That means packaging, product listings and digital commerce can work even more closely together to create a stronger consumer experience.
Quick commerce is becoming too large to ignore
The scale of the channel is now significant. Bain & Company estimates that India’s quick commerce market reached around $10 to $11 billion in GMV in 2025, after growing rapidly over the previous two years. Quick commerce accounted for around 16 to 17% of India’s total e-retail GMV. The shift in grocery is particularly important. According to Bain, online grocery penetration in India has increased roughly fivefold since quick commerce began scaling around 2020. In metro markets, e-grocery now accounts for around 6 to 7% of the grocery market.
NIQ provides another useful perspective. E-commerce accounts for around 11 to 13% of FMCG value sales in India’s metros, but contributes more than half of omnichannel FMCG growth. That is worth paying attention to. A channel does not need to account for the majority of sales to have a large influence on where future growth is coming from. For FMCG companies, quick commerce is increasingly becoming a cross-functional opportunity, influencing marketing, packaging, portfolio strategy and innovation alongside sales and distribution.
The monthly grocery basket is changing
Quick commerce is also changing the nature of the grocery purchase itself. Traditional household shopping has usually involved a degree of planning. Consumers make a weekly purchase, a monthly order or visit the neighbourhood kirana to replenish what they need.
Quick commerce adds a different kind of shopping behaviour. You run out of jeera while cooking. Friends are coming over and you need snacks. You decide to make biryani that evening. You realise in the morning that there is nothing for breakfast.
These are immediate purchases built around an occasion or a specific need. That matters for FMCG because these baskets may look very different from the traditional monthly grocery basket. Bain estimates that household essentials account for around 85 to 90% of quick commerce GMV, with top-up shopping being an important part of the channel. Smaller packs also play an important role in these purchases. NIQ has separately reported unit growth running ahead of FMCG volume growth, indicating greater consumer preference for smaller packs.
India has already seen how dramatically small packs can change categories. The sachet revolution was largely about affordability. Quick commerce could create a different reason for smaller packs to become important. This time, the reason may be convenience and immediate need. A consumer who has run out of an ingredient halfway through cooking may not want the largest value pack. She may simply want the right quantity to solve the immediate problem. This opens up an interesting question for brands. Why should the portfolio designed for a supermarket automatically be the right portfolio for quick commerce?
Over time, brands may have an opportunity to rethink pack sizes, bundles, product combinations and even products based on the shopping occasions that are emerging on these platforms. Quick commerce can become much more than another place where the same catalogue is uploaded. As consumer behaviour evolves, the assortment can evolve with it.
Advertising and the shelf are coming together
Quick commerce is also changing the relationship between advertising and trade marketing. Traditionally, advertising created awareness and demand. Trade marketing helped convert that demand inside the store.
The two functions were connected, but they operated in different environments. On quick commerce, they can happen in the same place. A sponsored search result is both advertising and shelf placement. A banner can introduce a product and take the consumer directly to the purchase page. A recommendation can improve discovery and conversion at the same time. Bain estimates that e-retail advertising accounted for around 25% of India’s digital advertising spend in 2025. That tells us something about where marketing budgets are beginning to move. For FMCG marketers, this creates a powerful opportunity because the distance between communication and purchase is extremely short. This also gives brands an opportunity to balance immediate conversion with long-term brand building, using discounts, offers and paid visibility alongside strong brand fundamentals.
Discounts can get the first order. The brand has to get the second.
Quick commerce makes promotions attractive because brands can see the impact quickly. Increase the discount. Improve the placement. Run an offer. Orders move. But an order and a relationship are not the same thing. A consumer buying a product because it is 25% cheaper today is very different from a consumer opening the app a month later and searching for that brand by name.
For FMCG companies, the long-term objective should be the second behaviour. The real value is created when the consumer remembers the brand, trusts the product and actively looks for it again. This is why quick commerce does not reduce the importance of traditional brand building. It increases it. A strong product, consistent quality, recognisable packaging, trust and a clear reason to choose still matter. The platform brings the consumer closer to the transaction, while the brand gives her a reason to come back.
Quick commerce can tell brands what consumers want
One of the most interesting possibilities is the amount brands can learn from the channel. Traditional FMCG businesses often work with delayed signals. Products move through distributors and retailers. Sales information takes time to reach the company. Consumer research happens periodically. A new product can be in the market for months before a clear pattern becomes visible.
Digital commerce makes that feedback cycle faster. Brands can begin understanding which products perform in different locations, what pack sizes consumers prefer, which variants work better, what products tend to be bought together and how demand changes around occasions. Used properly, this information can influence much more than advertising. It can help brands make decisions about assortment, pricing, pack architecture, innovation and new product development.
For an FMCG company, that makes quick commerce useful not just as a sales channel, but as a way of understanding consumers more closely. The brands that learn from this data and act on it quickly can gain a meaningful advantage.
Small brands can look big, and big brands can look small
For younger FMCG companies, quick commerce creates an interesting opportunity. Physical FMCG distribution has always rewarded scale. A large company may have decades of retailer relationships, lakhs of outlets and enormous advertising budgets. A young brand can now use the digital shelf to build visibility and enter the market more efficiently.
The digital shelf changes some of that. On a phone screen, a relatively young company and a category leader may occupy almost the same amount of space. The consumer can see both products and compare them within seconds. That gives younger brands an opportunity to enter the consumer’s consideration set far earlier than traditional distribution might have allowed.
At the same time, established brands have an opportunity to translate their existing awareness and equity into stronger digital visibility. Every search presents another opportunity to earn attention. For smaller brands, this creates an opportunity. For larger brands, it creates another place where they can strengthen their connection with consumers.
The real race is not about delivery time
Quick commerce will not replace India’s kiranas, supermarkets or conventional e-commerce. India will remain a deeply multi-channel FMCG market. Bain estimates that quick commerce now operates through more than 7,000 micro-fulfilment centres across over 200 cities, while also noting that the economics and adoption of the model outside major urban markets are still developing.
The point is not that every consumer will suddenly buy everything through quick commerce. The more interesting development is that one platform is beginning to bring together distribution, discovery, advertising, merchandising, consumer data and purchase. For FMCG companies, that makes quick commerce much more than a faster way of getting products to someone’s home. The more important question is not how quickly the product can be delivered. It is much simpler.