Brands
Honasa Consumer expects early thirties NSV growth in Q2 FY27
Mamaearth seen growing in high teens as younger brands accelerate to mid forties

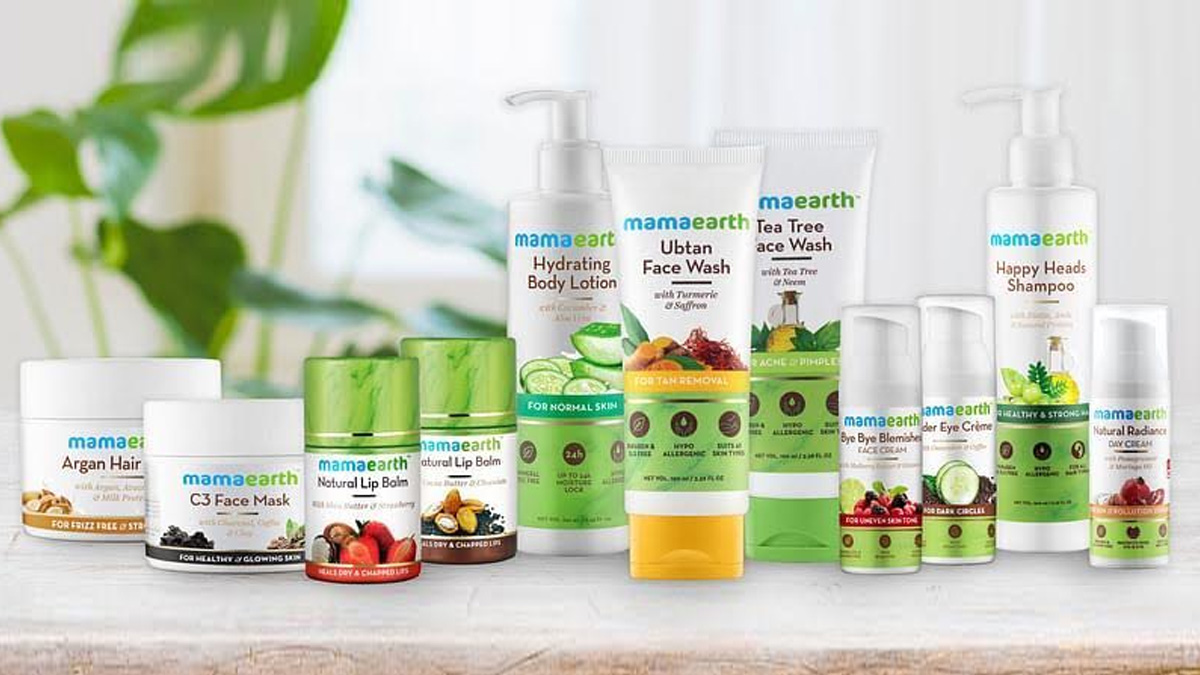
MUMBAI: Honasa Consumer is putting a little more gloss on its growth story, with the Mamaearth parent expecting net sales value (NSV) to rise in the early thirties year on year in the September quarter. Honasa Consumer Ltd expects consolidated NSV growth in the early thirties year on year for Q2 FY27, ended September 30, 2026, as growth remained broad-based across its portfolio of beauty and personal care brands. The company said the quarter is expected to build on the operating momentum recorded in Q1 FY27, although its financial results are still subject to approval by the Board.
The expected growth comes as Honasa continues to expand beyond Mamaearth, its flagship brand, and build a broader house of brands. Its current portfolio includes Mamaearth, The Derma Co, Aqualogica, BBlunt, Dr Sheth’s, Staze Beauty and Luminéve, spanning categories across skincare, haircare and colour cosmetics.
Mamaearth is expected to deliver high-teens year-on-year NSV growth in Q2 FY27. Honasa attributed the performance to continued brand affinity as well as the brand’s expanding offline footprint, suggesting that its largest business continues to grow even as the company leans more heavily on its newer brands.
The more interesting twist, however, is coming from the younger names in the portfolio. Honasa expects its younger brands to accelerate their NSV growth to around the mid-forties year on year in Q2 FY27, pointing to a broader contribution to growth rather than the company relying solely on Mamaearth.
That widening portfolio is increasingly important to Honasa’s growth strategy. The Derma Co, Aqualogica, BBlunt, Dr Sheth’s and Staze have allowed the company to operate across multiple beauty and personal care segments, while Luminéve adds another brand to the expanding portfolio.
While Honasa began life with a strong digital-first identity, offline distribution continues to be the key growth engine in the September quarter. The company expects both General Trade and Modern Trade to record strong growth during Q2 FY27, highlighting the importance of physical retail as it scales its brands.
General Trade growth is being supported by deeper direct distribution, according to the company. In Modern Trade, sharper execution at the point of sale is expected to support performance, while online channels are also expected to maintain their growth momentum.
The shift is significant for a company that describes itself as a digital-first house of brands. Honasa’s website says its omnichannel presence now extends across more than 750 districts, giving its brands a much wider physical footprint than their original online-first positioning might suggest.
The channel expansion also gives Honasa more avenues to take its younger brands beyond their existing consumer base. With General Trade, Modern Trade and online channels all contributing, the company is attempting to make its growth less dependent on any single route to the consumer.
Growth is not the only number Honasa is watching. The company expects to maintain an early double-digit operating margin in Q2 FY27, alongside strong year-on-year improvement, as it continues to work towards its broader objective of improving EBITDA margins.
The expected margin performance adds another layer to the September-quarter update. While NSV growth remains the headline number, maintaining an early double-digit operating margin would indicate that the company is looking to pair faster expansion with improving operating discipline.
Honasa, however, has made it clear that these are operating performance indicators rather than its final Q2 FY27 financial results. The company is awaiting Board approval of the results and said a detailed information update will follow once the quarter’s financial statements have been approved.
For now, the September quarter paints a picture of a company growing on several fronts at once. Consolidated NSV is expected to rise in the early thirties, Mamaearth is projected to grow in the high teens, younger brands are expected to accelerate to the mid-forties, offline distribution remains a key growth driver and operating margins are expected to stay in the early double-digit range.
That combination could prove important as Honasa continues to evolve from a Mamaearth-led business into a wider beauty and personal care house of brands. The September quarter, therefore, is less about one brand stealing the spotlight and more about the entire portfolio learning to share it.