e-commerce
RBI plans Digital Payment Intelligence Platform to tackle fraud
Governor Sanjay Malhotra calls for stronger AI safeguards as banks face increasingly complex digital fraud

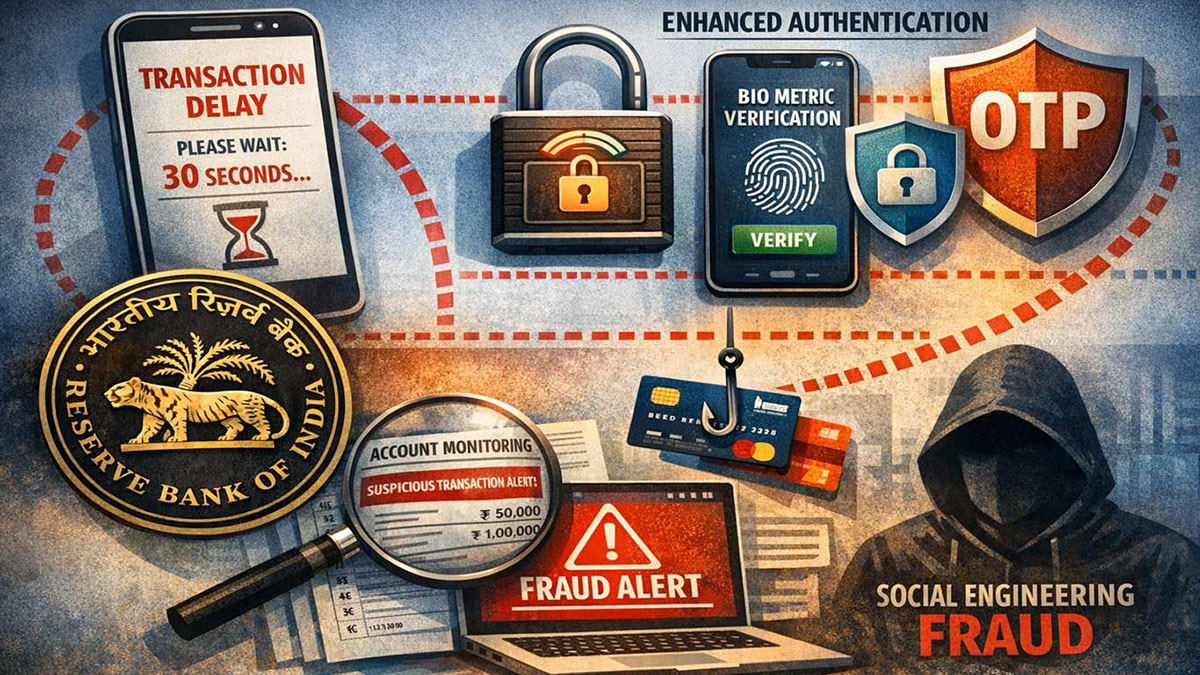
MUMBAI: The fraudsters are getting smarter, and the RBI wants the banks to keep pace. The Reserve Bank of India is preparing to give banks access to a Digital Payment Intelligence Platform as it looks to strengthen the financial system’s defences against increasingly sophisticated digital fraud, according to a CNBC TV18 report.
RBI Governor Sanjay Malhotra announced the initiative while speaking at the FIBAC 2026 conference in Mumbai on Tuesday, highlighting how artificial intelligence is increasingly being used on both sides of the fraud equation.
As banks expand AI use across fraud monitoring, lending and customer services, Malhotra said financial institutions must first understand where and how the technology is already being deployed before putting appropriate safeguards around it.
The issue is particularly relevant for smaller lenders that may not have the resources to develop their own AI models and instead rely on external technology providers. In such cases, banks will need stronger controls over customer data and tighter governance of third-party AI systems.
Malhotra called on banks to maintain a detailed inventory of the AI systems being used across their operations. He also recommended that boards formally approve AI governance frameworks, while banks should test their systems through red-team exercises and stress scenarios to identify potential weaknesses.
But as machines take on more work, the RBI does not want responsibility to disappear into the algorithm. Malhotra stressed that banks must remain accountable for decisions made using AI, with human intervention retained where appropriate.
The Governor also pointed to India’s existing digital financial infrastructure as a foundation for wider adoption of AI in financial services. The RBI is working to expand the Unified Lending Interface and Account Aggregator ecosystem, which could provide additional data and infrastructure for technology-driven financial services.
AI, Malhotra said, could accelerate financial inclusion, but poorly designed or inadequately monitored systems could have the opposite effect. Automated processes that fail to account for underserved consumers could create fresh barriers rather than remove them.
The Governor also highlighted regulatory changes introduced by the RBI over the past year across customer service, business operations and the cost of financial intermediation, as the central bank seeks to reduce regulatory friction while giving bank managements greater operational flexibility.
Its PRAVAAH regulatory platform has also been expanded, with greater automation of application-related processes. The RBI has additionally changed rules covering current accounts, working capital arrangements and bulk deposits.
On lending, Malhotra pointed to measures covering acquisition finance, priority-sector lending, project finance and alternative investment funds, aimed at improving access to credit across eligible sectors.
The proposed fraud intelligence platform, meanwhile, adds another layer to the RBI’s digital banking push using technology to fight technology before the numbers behind the next fraud start adding up.